SIMPLIFIED ACCOUNTING

Simplified accounting for sole traders, civil-law partnerships and selected partnerships

We maintain tax revenue and expense ledgers (PKPiR), revenue records for flat-rate income tax, VAT registers, Standard Audit File (JPK) submissions, social security (ZUS) settlements and other legally required records. We serve sole traders, civil-law partnerships and selected partnerships that are legally eligible to use simplified records.

We keep records up to date, monitor deadlines and data completeness, and communicate matters requiring decisions by the business owner, partners or those managing the business.
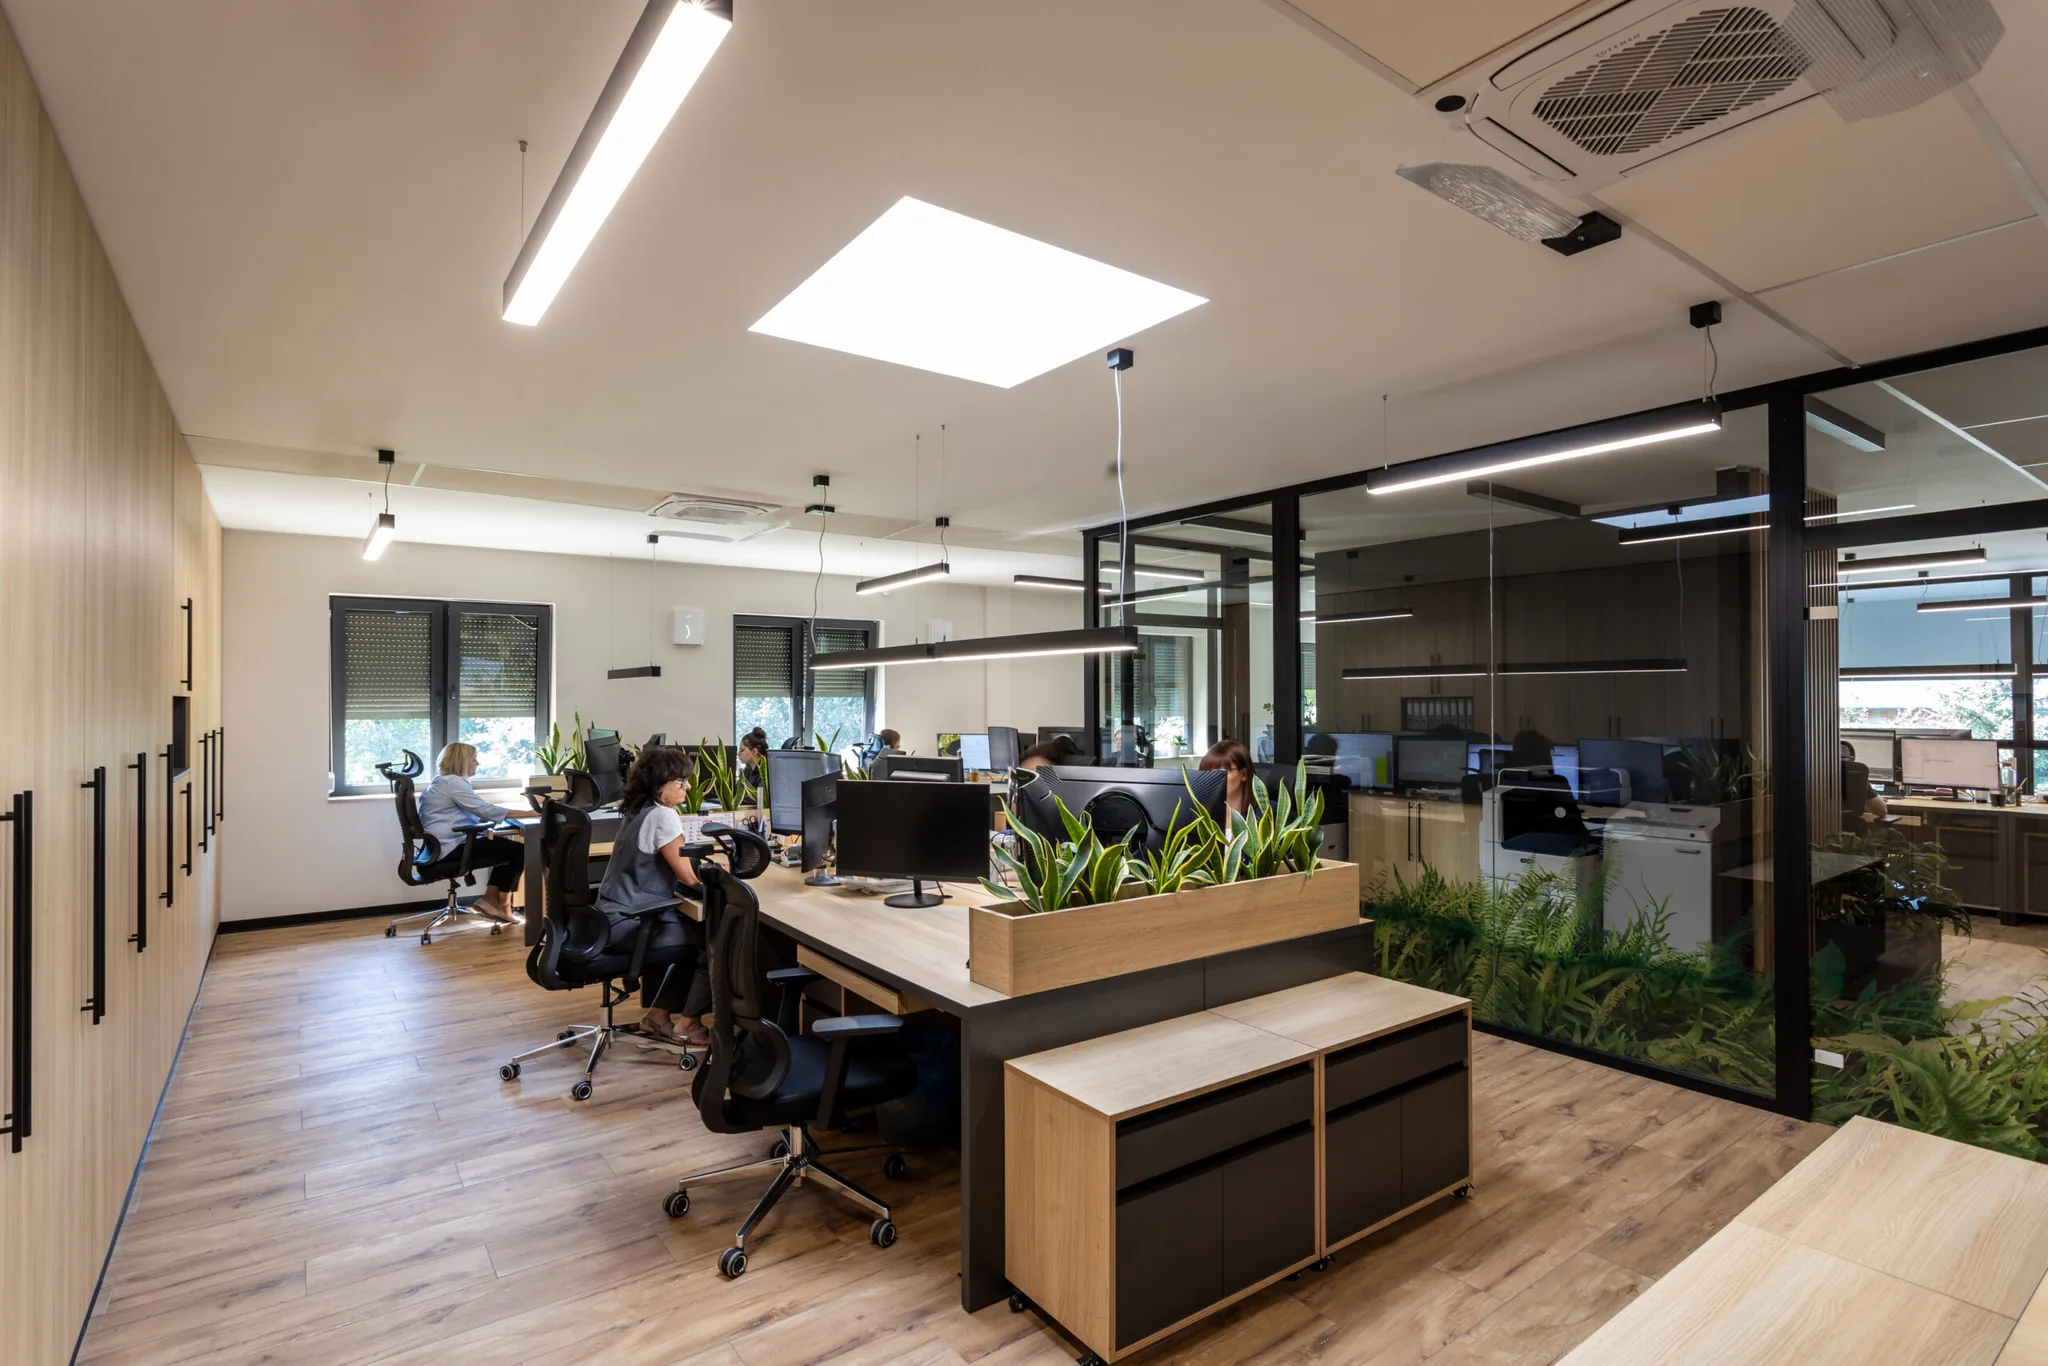
Accounting workstations at the SANDRA office

Simplified accounting does not
mean less
responsibility

The tax revenue and expense ledger (PKPiR) and revenue records for flat-rate income tax are simplified forms of record-keeping. They still require timely entries, complete documentation and correct classification of business transactions.

This applies to sole traders, civil-law partnerships and selected partnerships that are legally eligible to use simplified tax records.

At SANDRA, we treat simplified accounting as an organised service for a sole trader or partnership. We pay attention to documents, deadlines, VAT, Standard Audit File (JPK) submissions, social security (ZUS), fixed assets, thresholds and matters requiring decisions by the client.

Who is this service for?

Sole traders

We support people running sole-trader
businesses, including those providing services to
other businesses on a B2B basis.

Civil-law partnerships

We provide simplified accounting for civil-law partnerships, including
tax revenue and expense ledgers (PKPiR), revenue records for flat-rate income tax, VAT registers and other
legally required records, where the relevant tax arrangements apply.

Selected partnerships

We serve selected partnerships that are legally eligible to maintain simplified tax records instead of full accounting books.

PKPiR and flat-rate income tax

We support taxpayers using a tax revenue and expense ledger (PKPiR) or revenue records for flat-rate income tax, taking account of their ongoing tax and record-keeping obligations.

VAT taxpayers

We maintain VAT registers, prepare Standard Audit File (JPK) submissions and support sole traders and companies with ongoing VAT settlements.

Growing businesses

We support businesses that are growing, increasing their turnover or preparing to move to full accounting books.

Scope of services

We agree the scope of work individually, based on the legal form, tax regime, VAT status, number of documents,
staffing and the needs of the business or partnership.

Our service may include:

maintaining the tax revenue and expense ledger (PKPiR)

maintaining revenue records for flat-rate income tax

maintaining VAT registers

preparing Standard Audit File (JPK) submissions and legally required returns

handling social security (ZUS) settlements within the scope agreed with the client

maintaining fixed asset and intangible asset registers

accounting for vehicles, running costs and other typical business expenses

ongoing alerts about thresholds and obligations based on data supplied to our office

contacting the client when additional data or a decision is required

support with preparing your business for the National e-Invoicing System (KSeF)

support with changing your tax regime

support with moving from simplified accounting to full accounting books

Frequently asked questions about simplified accounting

A tax revenue and expense ledger (PKPiR) or flat-rate income tax: which should I choose?

The choice depends on your business activities, revenue, expenses and available tax reliefs. The tax revenue and expense ledger (PKPiR) records revenue and expenses for taxation under the progressive tax scale or the flat personal income tax rate. Under flat-rate income tax on revenue, tax is calculated on revenue without deducting business expenses. It is therefore helpful to compare the tax burden for your particular business. SANDRA supports businesses with changing their tax regime and maintaining the appropriate records.

For monthly settlements, the main deadlines are generally the 20th of the following month for personal income tax (PIT) advances or flat-rate income tax and social security (ZUS) contributions for sole traders, and the 25th of the following month for VAT and JPK_V7 for registered active VAT taxpayers.

If the taxpayer settles VAT quarterly, the VAT declaration covers the quarterly period, while the JPK_VAT record-keeping obligations may still apply monthly. For quarterly PIT or flat-rate income tax settlements, payment is generally due by the 20th day of the month following the quarter, and for quarterly VAT by the 25th day of the month following the quarter.

The annual personal income tax (PIT) return is generally due by 30 April of the following year. Documents should be provided to the accounting firm by the agreed deadline so that monthly or quarterly settlements can be prepared.

Nie zawsze. Wspieramy elektroniczny obieg dokumentów, dzięki któremu klient może przesyłać faktury i inne dokumenty księgowe bezpośrednio do biura oraz uzupełniać ich opis w systemie. Dokumenty można dostarczyć za pośrednictwem udostępnianych platform z komputera czy telefonu.

Opis dokumentu może obejmować m.in. cel wydatku, projekt, miejsce powstawania kosztu albo inne informacje potrzebne do prawidłowego księgowania. Elektroniczny obieg dokumentów usprawnia komunikację.

Check your business’s obligations, choose a tool for the National e-Invoicing System (KSeF), obtain access and grant the appropriate permissions to those responsible for invoicing and to your accounting firm. Then test issuing and receiving invoices and agree document-handling procedures. SANDRA helps prepare your business for KSeF within the scope agreed with you.

The obligation depends on the legal form and revenue. For sole traders and certain civil-law partnerships and other partnerships, full accounting books become compulsory from the next financial year if net revenue from sales of goods and products in the previous year reaches at least the equivalent of EUR 2.5 million expressed in Polish zloty. Polish limited liability companies and joint-stock companies must keep full accounting books regardless of this threshold. SANDRA monitors thresholds using the data supplied and supports the transition to full accounting books.